Credit Card Product Strategy
Asked of: Product Manager
Last updated
What's being tested
Interviewers probe your ability to design acquisition, promotion, and partnership strategies that balance unit economics, customer experience, and risk for a mid-tier rewards credit card. They want to see structured prioritization: target-segment selection, channel mix, funnel conversion targets, and quantified trade-offs (bonus size vs. payback). Capital One cares because small errors in assumptions scale to large losses or missed growth opportunities across millions of accounts.
Core knowledge
-
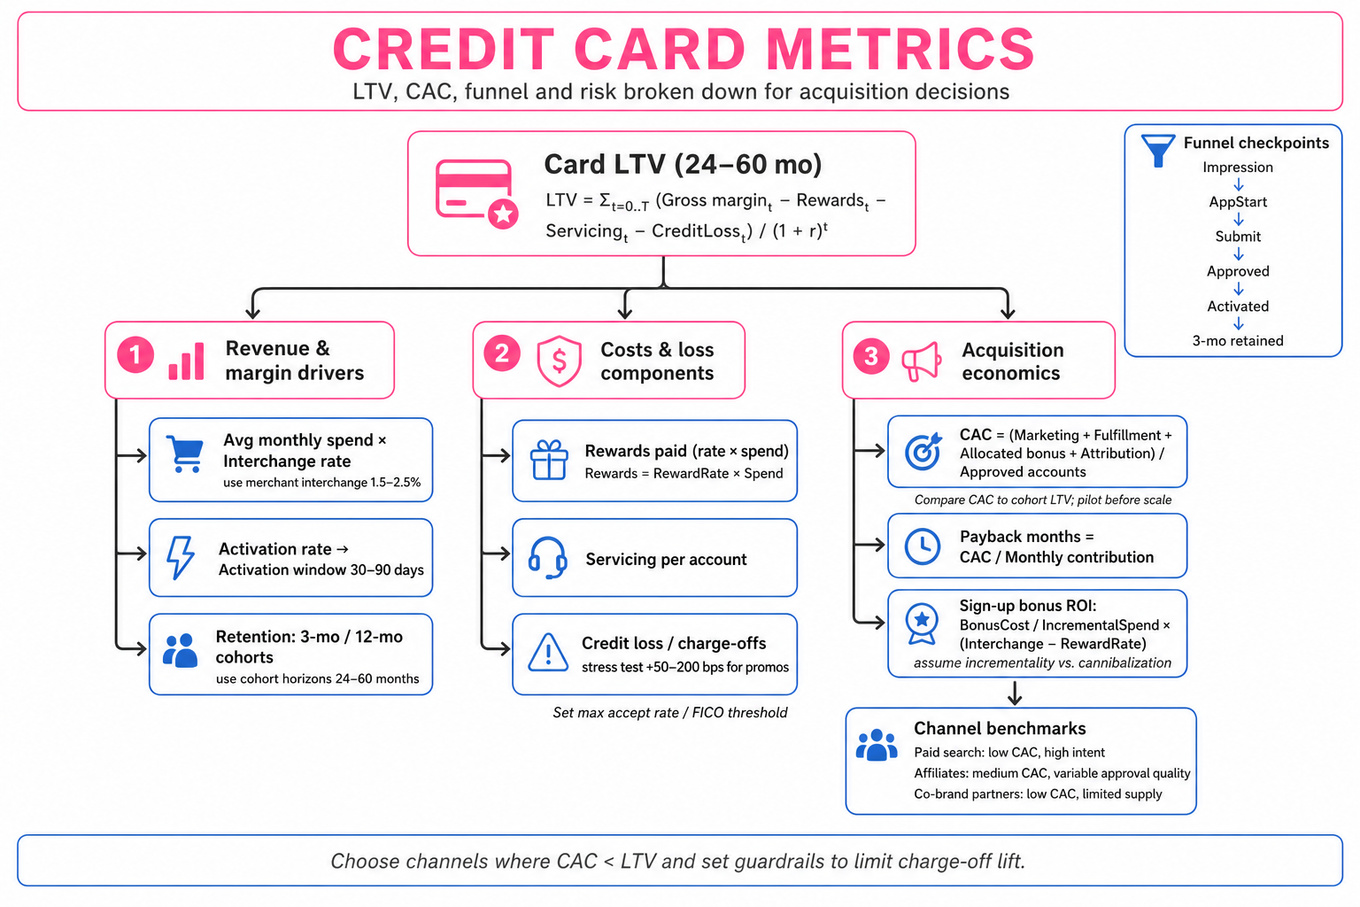
Customer Lifetime Value (LTV) — LTV = ∑_{t=0..T} (Gross margin_t − Rewards_t − Servicing_t − CreditLoss_t) / (1+ r)^t; use cohort horizons (24–60 months) for cards.
-
Customer Acquisition Cost (CAC) — CAC = (MarketingSpend + Fulfillment + BonusCostAllocated + AttributionOverhead) / NumberOfApprovedAccounts; compare to LTV and compute payback: PaybackMonths = CAC / MonthlyContribution.
-
Sign-up bonus ROI — Model bonus ROI as BonusCost / IncrementalSpendCaptured × (InterchangeMargin − RewardRate); assume incrementality (vs. cannibalization) and activation windows (30–90 days).
-
Incremental margin per customer — IncrementalMargin = Spend × InterchangeRate − Rewards − CreditLoss − Servicing; use merchant interchange % (e.g., 1.5–2.5%) and card-specific reward rates when modeling.
-
Funnel metrics & benchmarks — Track
Impression → AppStart → Submit → Approved → Activated → 3-mo Retained; use segment-level conversion assumptions (e.g., submit→approved 60–85% depending on cut). -
Channel economics — Paid search, affiliates, direct mail, digital display, partner co-brand have different
CAC, approval quality, and attribution windows; prioritize channels by CAC-to-LTV and supply-capacity constraints. -
Risk & underwriting guardrails — For acquisition pushes, define max accept rate, credit-score thresholds, and expected charge-off lift; use prospective stress (e.g., +50–200 bps delinquency) to set bonus caps.
-
Partnership valuation — For merchant deals, compute break-even customers = (DiscountPaid × ExpectedSpendingPerCard × MarginShare) / (IncrementalCardMargin); include strategic KPIs (brand lift, customer data).
-
Experimentation & pilots — Always pilot promotions with randomized holdouts or geo-splits; compute required N for key metrics (activation lift, incremental spend) and monitor upstream (application rate) and downstream (credit performance) signals.
-
Cannibalization & cohort-cross effects — Model cannibalization by estimating share of spend shifted from existing cards and cross-product migration; adjust incremental spend assumptions conservatively (e.g., 30–70% incremental).
-
Regulatory & operational constraints — Factor in disclosure/regulatory review cycles, fulfillment lead times, and operational capacity (call center, fraud ops); these can lengthen campaign ramp and increase costs.
-
Narrow KPIs to defend decisions — Choose 2–3 primary KPIs (e.g., Net New Active Accounts, 12-month Incremental Margin per Account, Payback Months) and supporting safety metrics (charge-off rate, bad-debt dollar).
Worked example — Capital One Credit Card: Acquisition & Promotion Strategy
First 30 seconds: ask clarifying questions — target geography, customer segment (mass-market vs. affluent), current funnel baselines (Impressions, AppStart, Submit, Approved, Activated), and approved channel CACs. Structure the answer around three pillars: segmentation, promotion mechanics & channel mix, and economics + guardrails. For segmentation, prioritize cohorts with high interchange and low expected credit loss (e.g., transactors with 12–18 months avg spend). For promotion mechanics, propose bonus size tied to achievable spend thresholds and an activation period to reduce fraud. For economics, show a simple P&L per cohort: CAC + Bonus + Fulfillment vs. expected incremental margin and compute payback months using . Flag the tradeoff explicitly: larger sign-up bonuses lift acquisition but may shorten payback and increase fraud/charge-offs, so cap based on maximum acceptable payback (e.g., 12 months) and real-time underwriting adjustments. Close by recommending a 90-day randomized pilot with pre-specified success thresholds and a post-pilot cohort analysis on 12-month incremental margin and credit performance; if more time, build a scenario Monte Carlo for delinquency sensitivity.
A second angle — Evaluate a Credit Card Partnership
A merchant partnership reframes acquisition as a revenue-share negotiation: quantify DiscountCost to merchant vs. IncrementalCardMargin for Capital One. Start by modeling customer-level economics: expected incremental transactions driven by merchant promotion, expected SpendPerCard at merchant, and discount paid per transaction. Determine break-even number of new accounts and churn-adjusted LTV uplift. Key constraints differ: merchant wants CPA-like guarantees or performance tiers; product focus shifts to tracking attribution windows, fraud prevention (promo abuse), and contractual protections (clawbacks). Recommend a small, timeboxed pilot that measures incremental card activations attributable to the merchant, with a sliding discount based on verified incremental spend.
Common pitfalls
Pitfall: Overstating incremental spend. A tempting mistake is treating all cardholder spend after acquisition as incremental. Always model cannibalization and baseline behavior; assume conservative incrementality unless you have causal A/B evidence.
Pitfall: Missing operational constraints. Presenting an aggressive campaign without considering underwriting capacity, fraud ops, or regulatory review undermines feasibility. State these constraints and how they change launch timelines and costs.
Pitfall: Not stating assumptions numerically. Saying “this will be profitable” without listing CAC, expected approval rate, activation, and churn loses credibility. Always show key assumptions and sensitivity ranges.
Connections
Interviewers may pivot to experimentation design (sample sizes, holdouts), credit risk management (loss forecasting, vintage analysis), or pricing strategy (rewards structure, interchange sensitivity). Be prepared to switch to metric-level analysis or operational rollout plans.
Further reading
-
[Customer-Based Corporate Valuation — Peter Fader] — rigorous framing for customer lifetime value and segmentation.
-
[A/B Testing by Kohavi et al.] — practical guidance on experimentation pitfalls and metrics selection.
Practice questions
Related concepts
- Fraud, Credit Risk, And Risk ControlsProduct / Decision Making
- Financial Services Compliance And Fair LendingProduct / Decision Making
- Customer Segmentation And Funnel StrategyProduct / Decision Making
- Business Strategy, Monetization, And PartnershipsProduct Design & Strategy
- Payments And Card Network Fundamentals
- Data-Driven Product DecisionsProduct / Decision Making